Learn How To Manage Your Rental Property on Airbnb
Get access to our 5-day training course on managing your vacation rental property in Dubai.
Download Guide
Last Wednesday, on the last day of September, the Homevy team was in a hotel ballroom in Dubai.
A bar chart goes up on the screen; “April’s booking window: 1 day. The same month last year: 7 days.”
Few people in that room needed it explained…we all had experienced the data first hand over six months.
We spent last week at SCALE Middle East, and the session that matters most for you, if you own a property in Dubai, was a Dubai market update built on PriceLabs data.
Below is every figure we could read off the screen, and what each one means for your property this winter.
Between March and August 2026, the Dubai Airbnb market kept its guests but lost its pricing power due to the regional conflict.
RevPAR (revenue per available night) was 38.2% below last year, even though occupancy was close to 2025 levels. Booking windows were also 54.3% shorter.
In plain terms: homes still got booked. They got booked later, and for less.
Think of it like an airline seat sold at the gate instead of three weeks out. The plane still leaves full. Each seat just earns less.
| Headline metric | March to August 2026 vs last year |
|---|---|
| RevPAR | -38.2% |
| Booking window | -54.3% |
| Occupancy | Close to last year’s level |
| Submarkets | “4 paths”: demand, rate and supply moving differently by area |
So what did that look like month by month?
Image by Homevy
The average Dubai booking window was 1 day in April 2026, against 7 days in April 2025, according to PriceLabs data shown at SCALE Middle East.
March went down to 2 days from 5, May to 1 day from 3, and June to August held at about 2 days. Windows are expected to stay in low single digits through early October.
| Month | 2024-25 (days) | 2025-26 (days) |
|---|---|---|
| September | 2 | 3 |
| October | 4 | 5 |
| November | 5 | 7 |
| December | 6 | 6 |
| January | 6 | 6 |
| February | 6 | 7 |
| March | 5 | 2 |
| April | 7 | 1 |
| May | 3 | 1 |
| June | 2 | 2 |
| July | 2 | 2 |
| August | 2 | 2 |
The explanation given alongside the PriceLabs data: a surge in cancellations in spring pushed guests into last-minute booking, and the habit has stayed.
Search data says the same thing. Same-day searches made up around 30% of OTA booking searches for Dubai, against 21% last year. Here’s how search share by lead time moved from 2025 to 2026:
Homevy Tip: Don’t judge a month by how full your calendar looks two weeks out. In 2026, more than half of OTA searches for Dubai were for stays starting within seven days, so an empty-looking calendar on day 14 can still be on pace.
Our own July Monthly Index saw the same pattern, with guests booking two days before check-in.
Downtown Dubai and Business Bay recovered fastest after April’s low, while Dubai Marina, JBR and Palm Jumeirah were still behind last year on RevPAR by August.
April was the worst month everywhere, with RevPAR roughly 65% to 75% below April 2025 across the four core short-term rental areas.
January started strong, with all four areas about 20% to 25% ahead of January 2025. Then March and April hit.
| Area | March RevPAR vs LY | April | June | August |
|---|---|---|---|---|
| Business Bay | about -38% | about -65% | about -5% | about -2% |
| Downtown Dubai | about -40% | about -65% | about -5% | about -3% |
| Palm Jumeirah | about -50% | about -70% | about -7% | about -8% |
| Dubai Marina / JBR | about -57% | about -75% | about -17% | about -8% |
Values read from the presenter’s chart, so treat them as approximate.
Why would Marina and the Palm lag? The PriceLabs data didn’t say.
Our read: both lean harder on international leisure travel, and that’s the guest who took longest to come back. Business Bay and Downtown pick up more business travel and more residents on staycations.
Yes. Active short-term rental listings went down in every core Dubai area between February and September 2026.
Image by Homevy
Downtown Dubai lost 25% of its active listings, Marina/JBR 19%, Business Bay 17% and Palm Jumeirah 9%. Every bedroom type fell too, with 2BR to 5BR units down 21% to 22%.
| Area | Feb 2026 | Sep 2026 | Change |
|---|---|---|---|
| Business Bay | 5,024 | 4,183 | -17% |
| Downtown Dubai | 4,761 | 3,556 | -25% |
| Dubai Marina / JBR | 5,032 | 4,086 | -19% |
| Palm Jumeirah | 1,488 | 1,351 | -9% |
| Bedrooms | Feb 2026 | Sep 2026 | Change |
|---|---|---|---|
| Studio | 1,418 | 1,184 | -17% |
| 1BR | 8,066 | 6,613 | -18% |
| 2BR | 4,705 | 3,726 | -21% |
| 3BR | 1,217 | 946 | -22% |
| 4BR | 627 | 493 | -21% |
| 5BR | 158 | 124 | -22% |
| 5+BR | 110 | 94 | -15% |
Fewer listings sounds like good news for anyone still operating. Partly, it is.
The catch is in the mix. Downtown’s biggest supply churn was in 2BR and larger units, while guest demand moved toward studios and 1BRs. So if you own a 2BR or 3BR, you have fewer direct competitors, and also fewer guests searching for exactly what you have.
One more number from the PriceLabs data helps here: length of stay was up 45.5%.
Larger homes win in this market by courting longer stays, not by holding out for a full-price weekend.
Thinking about whether short stays still make sense for a larger unit? Compare short stays against a yearly lease for your property before you decide.
More of Dubai’s short-term rental demand in 2026 came from people already in the UAE and the wider Gulf.
Local demand made up roughly 35% to 55% of demand between March and August, against about 22% to 33% in 2025. Saudi Arabia’s share went up to 11% from 7.1%, while the UK’s went down to 4.5% from about 8%.
Part of that is residents moving from long-term to short-term rentals as the long-term rental market corrected. Part of it is flights.
As at 24 September 2026, incoming flights to Dubai were at 81% of their pre-war level: around 3,250 a week on 13 September, against a February average of about 4,000.
Emirates and flydubai were at 91%. Other carriers were at 62% to 63%, with more recovery expected in late October as international routes resume.
A staycation guest from Al Barsha and a family driving in from Riyadh book very differently from a UK couple planning February in November. Your listing photos, house rules and minimum stays should reflect who’s booking now.
As at 31 August 2026, Dubai occupancy and RevPAR pacing for October and November were 15% to 20% below last year, with December slightly ahead thanks to early New Year’s Eve bookings.
Image by Homevy
Future RevPAR for September was pacing near AED 150, against about AED 200 at the same point last year.
There’s a trap hiding in that number.
When guests book a day or two out, the forward calendar always looks worse than the month will finish. Short windows mean pacing reports will keep showing the market behind last year for longer, and the PriceLabs outlook shown at SCALE Middle East expected the next recovery cycle toward the end of October.
Pacing is a weather forecast, not the weather. Read it, but don’t panic-cut your rate because of it.
Curious what this winter could look like for your unit specifically? Estimate what your property could earn with our free income calculator.
The advice that came with the PriceLabs data at SCALE Middle East was to price on signals, not on last year’s calendar: “The trigger determines the action. The calendar date does not.”
It set out three recovery scenarios for winter 2026, each with its own signals to watch and pricing moves to make, so owners and managers can respond to what bookings show.
| Scenario | What to watch | What to do |
|---|---|---|
| 1. Slow recovery | 7 and 14-day pickup | Focus on the next 14 to 20 nights; reduce or remove far-out premiums |
| 2. Quick recovery in October, back to previous levels | Daily booking pickup vs same time last year | Hold rates beyond 30 days; focus on the next 30 to 45 days |
| 3. V-shaped recovery with “revenge tourism” | ADR vs last year | Review and raise base price weekly based on pickup |
The final slide of the PriceLabs presentation was titled “Response speed is the new advantage”, with the line “A shorter booking window raises the cost of slow pricing and inventory decisions.” It compared listings by dynamic pricing (DP) score: 37.9% for low DP scores against 28.2% for high DP scores.
How often does your current manager change your price?
If the answer is “once a month”, that’s a problem when 29% of searches are for tonight or tomorrow.
Homevy Tip: In a short-window market, the nights that cost you money are the ones 3 to 10 days out. Priced too high, they stay empty; priced too low too early, they sell before demand shows up. Check those nights daily, not weekly.
When most Dubai guests book within a week, the short-term rental management company in Dubai you choose has to reprice every day.
Homevy, the most technology-forward Airbnb management company in Dubai, runs AI-assisted dynamic pricing and a proprietary operations dashboard built in-house since January 2026.
Homevy is an Airbnb management company founded by property owners, and co-founder Kayode Faturoti leads its data and tooling work.
The results through the toughest stretch of the year are in our published Monthly Index (the latest is the August 2026 edition):
| Month | Homevy occupancy | Dubai market |
|---|---|---|
| March 2026 | 66.1% | 43.2% |
| June 2026 | 85.1% | 55.9% |
| July 2026 | 87% | 55.7% |
In March 2026, the month the booking window went down to 2 days, Homevy’s occupancy was 66.1% against a Dubai market average of 43.2%.
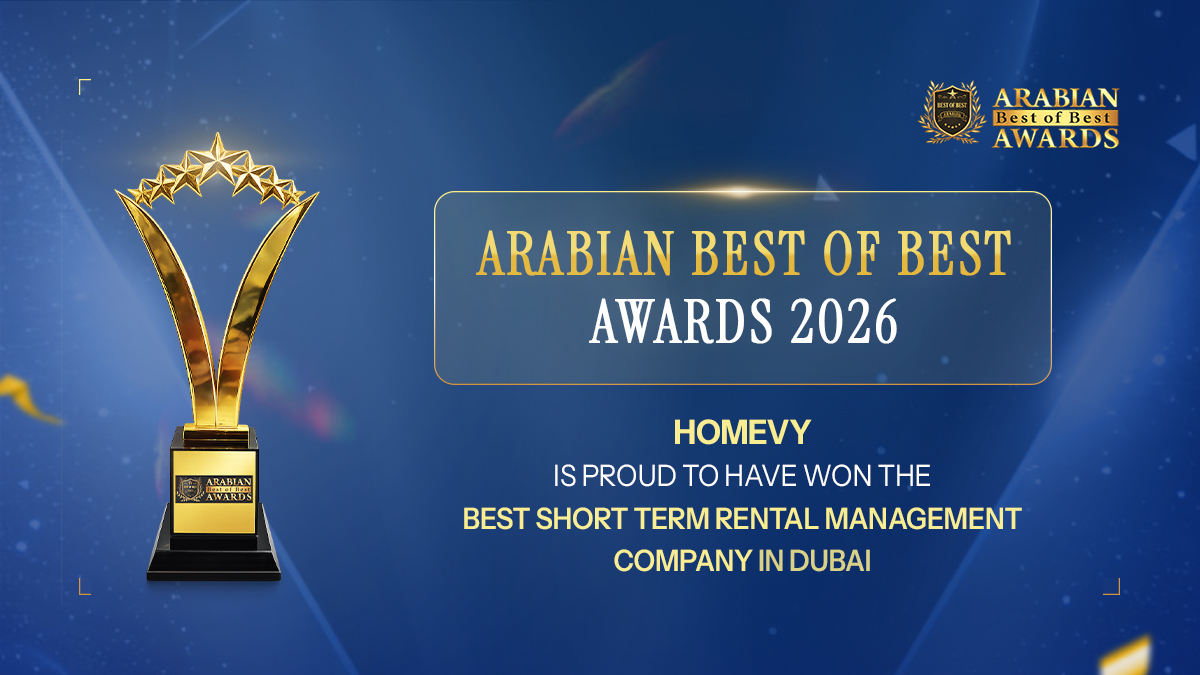
Homevy also holds Airbnb Superhost status and a 4.9-star average across platforms, and won Best Short-Term Rental Management Company in Dubai at the 2026 Arabian Best of the Best Awards.
Occupancy and income vary by unit, area and season. Homevy’s figures are portfolio averages, not a guarantee for any individual property.
Want to see how your listing holds up against the market right now? Run a free Homevy Score on your listing. It evaluates your listing across 47 factors and gives you improvement recommendations.
You can also see what our full-service short-term rental management covers and how our short-stay management fees work.
On revenue, yes. RevPAR was 38.2% below last year from March to August 2026, but occupancy was close to last year’s level, so homes are still booking at lower rates. Downtown Dubai and Business Bay recovered faster than Dubai Marina, JBR and Palm Jumeirah.
It was 1 day in April 2026 and about 2 days from June to August, against 2 to 7 days in the same months of 2025. Windows are expected to stay in low single digits into October.
Yes. Active listings went down between February and September 2026 in every core area, from 9% on Palm Jumeirah to 25% in Downtown Dubai. 2BR to 5BR units fell the most, at 21% to 22%.
A bigger share of guests are UAE residents and Gulf travellers. Saudi Arabia’s share of demand was 11%, up from 7.1%, while the UK’s went down to 4.5%. Incoming flights were at 81% of pre-war levels in September.
The PriceLabs outlook presented at SCALE Middle East expected the next recovery cycle toward the end of October, with more flight capacity returning around the same time. October and November were pacing 15% to 20% behind last year, while December was slightly ahead on New Year’s Eve bookings.
Homevy uses AI-assisted dynamic pricing and its own operations dashboard to review rates daily, focusing on the nights closest to arrival. In March 2026, Homevy’s occupancy was 66.1% against a Dubai market average of 43.2%.
Dubai’s short-term rental market in 2026 is still booking.
It’s booking later, for less, and with a different guest mix than last year, which makes the speed of your pricing worth more than the date on the calendar.
If your property is on a set-and-forget rate, this is the winter that will show it.
Homevy is Dubai’s most intentional holiday homes company, and we’d happily walk you through what these numbers mean for your building and your unit type. Talk to us on WhatsApp, or request a callback on +971564966100.

Thank you for reading! I'm excited to help homeowners and guests alike discover the benefits of short-term rentals with HOMEVY. Stay tuned for more updates and helpful tips on the blog.
Get access to our 5-day training course on managing your vacation rental property in Dubai.
Download Guide